You may be able to buy before you sell in Colorado by qualifying with both properties, using a bridge loan or home-equity strategy, making a sale-contingent offer, or coordinating the two closings. The best path depends on equity, income, credit, cash reserves, timing, and the risk you are willing to accept.
This guide compares the primary buy-before-you-sell strategies and shows how real Colorado buyers used different approaches based on their equity, income, property, and moving timeline.
Buy Before You Sell in Colorado Guide
Coordinate the Purchase and Sale Before You Make an Offer
We can compare available equity, the temporary payment, cash to close, loan qualification, expected sale proceeds, and what happens if the current home takes longer to sell.
Borrow against eligible equity in the current home for the next purchase
Access equity before the sale closes
Short-term cost, sale timing, and payoff risk
HELOC or home-equity loan
Open a second lien against the current residence before or during the sale process when permitted
Can preserve the existing first mortgage
Qualification, draw timing, variable-rate risk, and listing restrictions
Sale-contingent offer
Make the new purchase dependent on selling the current home
Reduces double-payment and bridge risk
May be less competitive with the seller
Coordinated sale and purchase
Align both closings, possibly with a rent-back or temporary housing plan
Uses sale proceeds directly
Multiple transactions must perform on schedule
How to Buy Before You Sell in Colorado
This short video explains how homeowners may be able to unlock equity, avoid a home-sale contingency, and move once instead of coordinating two closings on the same day.
Option 1: Qualify With Both Properties
Some buyers have enough income, credit, cash, and reserves to qualify for the new mortgage while keeping the current home until after closing. This can be the cleanest structure when the down payment is already available.
The analysis includes the current mortgage, taxes, insurance and association dues, proposed new housing payment, other monthly debts, cash needed for the new purchase, post-closing reserves, and how the new mortgage will be handled after the current home sells.
Recast or principal reduction after the sale
After the current home sells, a buyer may choose to apply proceeds to the new mortgage. A large principal payment reduces the balance but does not automatically reduce the required monthly payment. Some servicers permit a mortgage recast after an eligible principal reduction, subject to timing, fee, loan type, and servicing rules.
Option 2: Use a Bridge Loan
A bridge loan is a short-term loan secured by eligible equity, commonly in the current home. Proceeds may be used for a down payment, closing costs, or another permitted purchase purpose.
Important terms include the maximum combined loan-to-value ratio, valuation method, available loan amount after existing liens and deductions, term, maturity, rate, fees, required payment, reserves, listing rules, extension provisions, and the plan if the home does not sell on time. See the detailed Colorado bridge-loan guide.
Option 3: Use a HELOC or Home-Equity Loan
A HELOC or home-equity loan may allow a homeowner to access equity while keeping the existing first mortgage in place. This can be attractive when the current first-mortgage rate is materially below the cost of replacing it.
The second-lien payment can affect qualification for the new home, and a HELOC commonly has a variable rate. Listing status, draw timing, early-closure terms, appraisal or valuation requirements, and the payoff process also matter.
Option 4: Make a Sale-Contingent Offer
A sale contingency can reduce the risk of owning two homes or taking short-term financing. The tradeoff is negotiating strength. A seller may prefer an offer without a home-sale contingency, particularly when multiple buyers are competing.
The contingency may be more acceptable when the current home is already under contract and major milestones have been completed. Your real estate agent should advise on contract language, deadlines, kick-out provisions, and local market conditions.
Option 5: Coordinate Both Closings
A same-day or closely coordinated sale and purchase can allow the existing-home proceeds to fund the next closing. This may also require temporary occupancy, a post-closing rent-back, moving coordination, wire timing, or a backup housing plan.
This approach can reduce borrowing but increases operational dependence. A delay in the sale may affect the purchase, so the title companies, lenders, agents, movers, and all parties need a clear timeline.
Real Colorado Buy-Before-Selling Stories
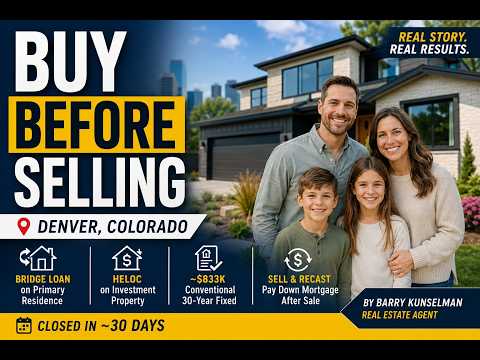
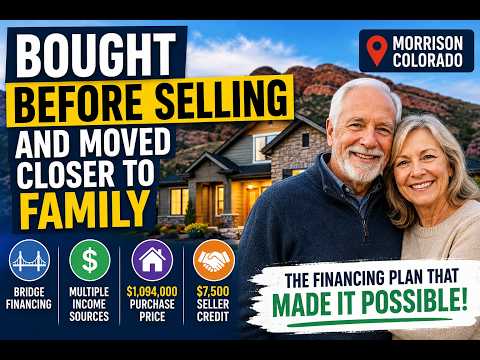
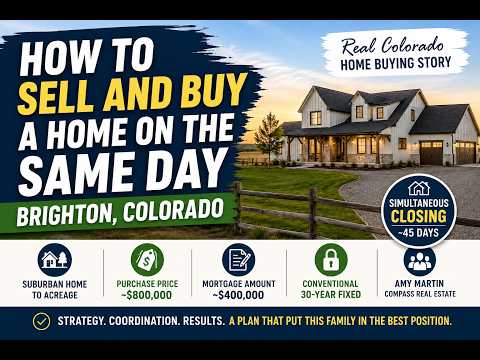
These anonymized transactions show why there is no single buy-before-sell formula. One family combined two equity sources and planned a recast, another used bridge financing while coordinating multiple forms of income, and another avoided bridge financing by aligning the sale and purchase closings.
Bridge loan, HELOC, and recast
Buying an approximately $1.3 million Denver home first
A young family accessed equity from its current residence and an investment property, kept the new first mortgage conventional, and planned to apply sale proceeds and request a recast after the prior home sold.
A couple used current-home equity, employment income, retirement income, eligible assets, a conventional 30-year fixed mortgage, and a seller credit to buy the Morrison home before selling.
A move-up family sold its suburban home, transferred the available equity into the new down payment, and purchased a Brighton property on acreage without adding bridge financing that the final plan did not require.
These stories are educational examples, not promises of approval, identical terms, identical timelines, or identical results.
A Practical Colorado Example
Assume a homeowner expects to sell the current property for $800,000 and owes $300,000. The replacement home is expected to cost $650,000, and the buyer wants to use $200,000 of current-home equity for the down payment and closing.
The apparent gross equity is $500,000, but that is not the same as usable bridge proceeds or final net sale proceeds. The analysis should include estimated selling costs and concessions, existing liens, bridge or HELOC maximum leverage, interest and fees, purchase cash to close, temporary monthly payments, required reserves, and lower-price or delayed-sale scenarios.
Before buying, know what happens if the current home sells for less, takes longer, falls out of contract, or does not sell before a short-term loan matures. A strategy is only strong when the delayed-sale scenario remains manageable.
How I Analyze a Buy-Before-Sell Scenario
Estimate net equity: Expected sale price minus liens, selling costs, concessions, and a conservative cushion.
Determine liquidity needed: Down payment, closing costs, reserves, repairs, and moving expenses.
Test qualification: Current and new housing obligations, bridge or HELOC payment, income, debts, credit, and assets.
Compare strategies: Carry both homes, bridge, HELOC, sale contingency, or coordinated closings.
Model timing: Listing date, expected market time, contract period, closing, and short-term loan maturity.
Stress the sale: Lower price, longer market time, repair request, appraisal issue, or failed contract.
Plan the proceeds: Retain cash, pay down the new loan, request a recast when eligible, or evaluate a future refinance.
Questions to Answer Before Writing the Offer
How much usable equity is available?
Can you qualify while carrying both homes?
How much cash must remain after closing?
Can the current home be listed during the financing process?
Is an appraisal or another valuation required?
What is the short-term loan maturity date?
What are the extension and default provisions?
Will the new mortgage be recast, paid down, or refinanced after the sale?
What happens if the sale price is lower than expected?
What is the maximum temporary monthly obligation?
Frequently Asked Questions About Buying Before Selling in Colorado
Do I need the new purchase contract before applying for bridge financing?
It depends on the program. Some lenders can review the borrower and current property before the replacement contract, while others need the new transaction details before final approval or funding.
Can my current home stay on the market?
Program rules vary. Listing status can affect HELOC, home-equity, bridge, and other financing. Confirm the rule before listing or changing the listing status.
How is the bridge loan amount calculated?
A lender commonly starts with an eligible percentage of the current home’s value, then subtracts existing liens, required reserves, fees, interest, or other program deductions. The exact formula is program-specific.
What if my current home does not sell?
The bridge loan still has a maturity date and contractual remedies. Understand extension options, additional costs, refinance alternatives, and the consequences of missing the payoff deadline.
Can I use sale proceeds to lower the new mortgage payment?
Possibly. A principal reduction lowers the balance. Lowering the required payment generally requires an eligible recast or refinance. Confirm servicing rules before relying on this strategy.
Compare Ways to Buy Before You Sell in Colorado
See available equity, payment, cash to close, qualification, costs, and delayed-sale risk side by side.
This page is for general educational purposes and is not a rate quote, approval, commitment to lend, financial advice, tax advice, legal advice, real estate advice, or investment advice. Bridge, HELOC, home-equity, recast, reserve, listing, appraisal, payment, maturity, and program requirements vary and can change. All financing is subject to borrower, credit, income, asset, property, lender, and investor approval. Not all applicants or properties will qualify.
A lower house payment starts with the decisions you make before you buy.
When mortgage rates stretch your budget, shopping for a home needs to include more than the asking price. We need to look at how you buy, which property you choose and every meaningful expense that will go into your monthly payment.
Michael and Melissa are always a pleasure to work with. They are extremely responsive, professional and work hard to get the best loan for us. I would recommend Colorado Mortgage to anyone. Thank you for another great experience!