By Michael Shotnik | Milestone Home Mortgage
Mortgage preapproval conditions are the facts, documents and remaining reviews that stand b...
Bridge loans in Colorado can provide short-term access to eligible home equity before the current property sells. They may help fund the down payment or closing on a replacement home, but the loan amount, payment, maturity date, costs, listing rules, and delayed-sale risk must be understood before you rely on one.
This guide explains how bridge loans in Colorado commonly work, how they compare with a HELOC or coordinated closing, and how real Colorado buyers used bridge financing as part of a larger purchase strategy.
We can estimate available proceeds, the short-term payment, purchase cash to close, expected sale payoff, and what happens if the home takes longer to sell.
Schedule a Bridge-Loan Consultation Start a Secure ApplicationA residential bridge loan is short-term financing designed to bridge the period between two transactions. In a buy-before-you-sell scenario, the loan is commonly secured by the current home and paid off when that home sells or from another approved source.
Bridge proceeds may be used for an eligible down payment, closing costs, debt payoff required by the program, or another approved purpose connected to the replacement purchase. The exact use of proceeds depends on the lender and transaction.
A common framework begins with a permitted percentage of the current property’s value, then subtracts existing liens and other required deductions.
Eligible percentage of value minus existing liens minus program deductions equals potential bridge proceeds
Program deductions may include interest reserves, fees, required equity, closing costs, or other amounts. The lender may use an appraisal, automated valuation model, broker price opinion, or another approved valuation method.
Assume a home is valued at $800,000, the program permits a maximum combined leverage of 75 percent, and the existing mortgage balance is $300,000.
The simple calculation suggests up to $300,000 before deductions. It does not guarantee that amount. Credit, income, assets, the sale plan, lien position, property, loan minimums, and replacement transaction can affect the result.
Potential structures include a second mortgage behind the current first mortgage, a new first-lien bridge loan that pays off the existing mortgage, an interest-only loan, a loan with monthly payments, a structure with an interest reserve, a cross-collateralized loan involving more than one property, or a bridge combined with the new purchase mortgage.
The lien position and payment structure affect available proceeds, qualification, cost, and the eventual payoff process.
Costs can include interest, origination points or lender fees, appraisal or valuation fees, title and settlement charges, recording fees, prepaid interest or an interest reserve, extension fees, and any permitted minimum-interest or early-payoff provisions.
Because the loan is intended to be short term, annual percentage rate is not the only useful comparison. Estimate the total dollar cost for a realistic sale period and for a delayed-sale scenario.
Some do. Others may reserve interest, accrue interest, or structure payments differently. The borrower should know the required monthly payment, when interest begins accruing, whether interest compounds, how the payoff is calculated, whether unused proceeds accrue interest, and how the bridge obligation is treated when qualifying for the replacement mortgage.
Listing rules are program-specific. Some bridge programs are designed for homes that are already listed or under contract. Some HELOC and home-equity lenders restrict new applications after a property is listed. Confirm the financing plan before listing, withdrawing, relisting, or accepting a contract because a change in status can affect eligibility.
Some lenders can review the borrower and current property before the replacement contract is signed. Final approval or funding may still require the purchase contract, title work, settlement statement, new mortgage approval, and specific cash-to-close details.
Starting early can identify equity, documentation, credit, and timing issues before the buyer is operating under a short contract deadline.
| Factor | Bridge loan | HELOC |
|---|---|---|
| Primary purpose | Short-term transaction timing and equity access | Revolving home-equity access |
| Term | Usually shorter | Often a longer draw and repayment structure |
| Rate | Program-specific fixed or variable structure | Commonly variable |
| Listing status | May be designed for a listed sale, depending on the program | Some lenders restrict applications on listed property |
| Cost | Can include short-term points, fees, and extension charges | May have lower upfront cost but annual, early-closure, and variable-rate considerations |
A bridge loan may not be necessary when the buyer already has the required purchase cash and can qualify while carrying both housing payments. Avoiding a bridge can reduce fees and complexity.
A bridge may be valuable when the buyer can qualify for the overall transaction but does not have enough liquid cash for the down payment, or when accessing equity allows the permanent first mortgage to be structured more effectively.
A sale-contingent offer reduces short-term borrowing and double-payment exposure, but it can be less competitive. Bridge financing can help remove the home-sale contingency, but it replaces that contract risk with financing cost and sale-timing risk.
Your real estate agent should advise on the local market and contract terms. The mortgage analysis should show the cost of improving the offer’s financing certainty.
For independent guidance on reviewing loan estimates, closing costs, and mortgage terms, see the Consumer Financial Protection Bureau homebuyer resources.
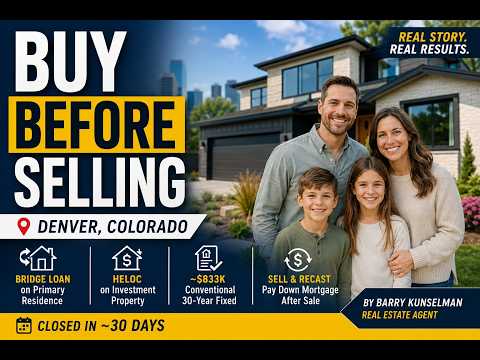
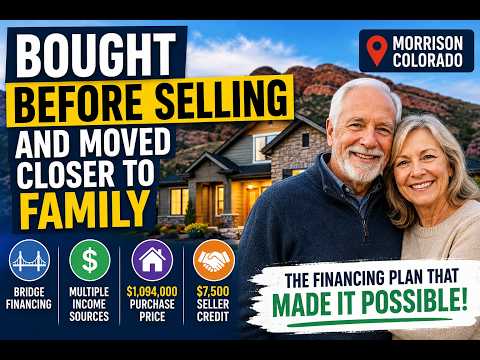
These anonymized purchases show different ways bridge financing can support a move, from funding a cash purchase to working alongside a permanent mortgage and a post-sale plan.
Featured Home Buying Story • Cañon City Purchase
A HELOC did not work because of income qualification. Instead, a bridge loan secured by the buyers’ existing home closed first, providing the funds for a Cañon City cash purchase without a home-sale contingency.
Read the Full Cañon City Story
An individual transaction, not a guarantee of eligibility, terms, timing, or results. Bridge financing carries costs and a repayment deadline.
These are educational examples, not promises of bridge eligibility, identical terms, identical timelines, or identical results.
A bridge loan is not designed to remain outstanding indefinitely. Review the maturity date, extension terms, default provisions, and refinance alternatives before closing. The plan must remain workable if the sale is delayed.
The settlement agent generally obtains a payoff for the bridge loan and other liens. Sale proceeds pay transaction costs and liens before the remaining funds are delivered to the seller.
Remaining proceeds may be retained as reserves, applied to the new mortgage balance, used to request an eligible recast, used for improvements, or incorporated into a future refinance decision. A large principal payment does not automatically reduce the required monthly payment, so recast or refinance options should be confirmed separately.
Terms vary by lender and program. Residential bridge loans are generally short term and must be matched to a realistic sale and payoff schedule.
Often yes, subject to program minimums. Borrowing less can reduce interest and fees. The goal is to solve the liquidity need, not automatically maximize the debt.
Some programs review income and debt-to-income ratios, while others place more emphasis on equity, assets, and exit strategy. The replacement mortgage may have separate qualification requirements.
Many programs require an appraisal or another approved valuation. The method depends on the lender, property, loan amount, and timing.
Potentially, subject to the program and purchase-loan rules. The source and transfer of funds must be documented.
The sale must still pay required liens and costs. A lower price can reduce remaining proceeds or require additional cash. Model a conservative sale price before borrowing.
See available proceeds, payment, costs, purchase cash, maturity date, and delayed-sale risk side by side.
Schedule a Bridge-Loan Consultation Start a Secure ApplicationThis page is for general educational purposes and is not a rate quote, approval, commitment to lend, financial advice, tax advice, legal advice, or real estate advice. Bridge-loan rates, fees, terms, leverage, payments, listing rules, maturity, extension provisions, valuation, and eligibility vary by lender and can change. All financing is subject to borrower, credit, income, asset, property, title, lender, and investor approval. Not all applicants or properties will qualify.
By Michael Shotnik | Milestone Home Mortgage
Mortgage preapproval conditions are the facts, documents and remaining reviews that stand b...
Michael and Melissa are always a pleasure to work with. They are extremely responsive, professional and work hard to get the best loan for us. I would recommend Colorado Mortgage to anyone. Thank you for another great experience!
Milestone Home Mortgage LLC NMLS #2588937. Michael Shotnik NMLS: 218281, CO License: 100017466. Not licensed in Alaska or New York. To check license status of mortgage loan originator, visit D.O.R.A. and NMLS consumer access.