FHA loans in Colorado can be a strong option for eligible homebuyers who need a low down payment, additional credit flexibility, or a more forgiving debt-to-income analysis. FHA is not automatically the best first-time-buyer loan, so it should be compared with conventional, VA, and down-payment-assistance options using the full payment and cash-to-close picture.
FHA Loans in Colorado Guide
Compare FHA With Conventional and Assistance Options
See the down payment, mortgage insurance, interest-rate pricing, closing costs, seller-credit limits, and long-term payment side by side.
An FHA loan is a mortgage made by an approved lender and insured by the Federal Housing Administration. FHA insurance reduces the lender’s risk, which can make financing available under guidelines that differ from conventional loans.
FHA financing may be used for an eligible one-unit primary residence, two-to-four-unit owner-occupied property, approved condominium, manufactured home, refinance, or renovation transaction. It is not designed for a standard second-home or non-owner-occupied investment purchase.
FHA Loans at a Glance
Potential minimum investment
3.5% for an eligible borrower
Occupancy
Principal residence
Mortgage insurance
Upfront and annual premiums generally apply
Loan limits
County and unit-count specific
How Much Is the FHA Down Payment?
Eligible borrowers may be able to purchase with a minimum required investment of 3.5 percent. Credit history, score, automated underwriting, compensating factors, lender overlays, property eligibility, and the source and transfer of funds all matter.
A lower score does not automatically mean FHA is the only option, and a higher score does not guarantee approval. Conventional or another program may still produce a better result after mortgage insurance, pricing, cash to close, and the expected ownership timeline are compared.
A $500,000 FHA Purchase Example
Item
Illustrative amount
Important note
Purchase price
$500,000
Must be supported by the contract, appraisal, and applicable loan limit
3.5% down payment
$17,500
The source and transfer of funds must be documented
Base loan amount
$482,500
Before any financed upfront mortgage-insurance premium
Closing costs and prepaids
Varies
Seller credits, lender credits, assistance, taxes, insurance, and the closing date can affect the total
This example does not include an interest rate, monthly payment, mortgage-insurance amount, or final cash-to-close figure because those depend on the borrower, property, market date, pricing, taxes, insurance, and approved structure.
How FHA Mortgage Insurance Works
FHA loans generally include an upfront mortgage-insurance premium and an annual mortgage-insurance premium collected through the monthly payment. The amount and duration depend on the loan term, loan-to-value ratio, origination date, and current FHA rules.
Do not assume FHA mortgage insurance disappears automatically at 80 percent loan-to-value. When comparing FHA with conventional financing, review the base loan amount, financed upfront premium, monthly insurance, rate and points, total housing payment, cash to close, and likely time before a sale or refinance.
FHA Credit and Debt-to-Income Flexibility
FHA underwriting can be more flexible than conventional underwriting in some scenarios, but it still requires an acceptable credit history and demonstrated ability to repay. Underwriting may review housing-payment history, revolving and installment debts, collections, prior housing events, recent credit activity, employment stability, available reserves, and the increase from the current housing payment to the proposed payment.
There is no single debt-to-income percentage that guarantees approval. Automated underwriting findings, credit, reserves, income stability, property, and lender requirements all matter. The approved payment should also be compared with the borrower’s comfortable payment and household budget.
FHA Property and Appraisal Requirements
An FHA appraisal estimates market value and evaluates whether the property appears to meet FHA minimum property requirements. It is not a substitute for a professional home inspection.
Potential issues can include health or safety hazards, peeling paint in certain older homes, roof or structural concerns, electrical or plumbing problems, heating, utilities, water or septic systems, unpermitted additions, incomplete construction, condominium eligibility, and manufactured-home foundation or title requirements.
FHA Loan Limits in Colorado
FHA loan limits vary by county, number of units, and year. The correct limit must be checked for the property address and anticipated closing year. High-cost counties may have higher limits than standard-limit counties.
Gift Funds, Down Payment Assistance, and Seller Credits
Subject to documentation and program requirements, FHA funds may include borrower savings, eligible gifts, approved grants or deferred second mortgages, employer or government assistance, permitted seller credits, and lender credits.
The table below is a quick orientation. For a complete decision framework covering down payment, credit, debt-to-income analysis, mortgage insurance, property rules, seller credits, closing costs, and long-term tradeoffs, read the full FHA versus conventional loan comparison.
Factor
FHA
Conventional
Potential minimum down payment
3.5% for an eligible borrower
Potentially 3% for certain eligible buyers
Mortgage insurance
Upfront and annual FHA mortgage insurance
Risk-based private mortgage insurance when required
Credit sensitivity
May provide additional flexibility in some scenarios
Pricing, PMI, and approval can be highly credit-sensitive
Property standards
FHA appraisal and property requirements
Conventional appraisal and investor requirements
Insurance removal
Duration depends on FHA rules and loan structure
PMI may be cancelable under applicable rules
For a deeper cost and qualification review, use the complete FHA vs. conventional loan comparison, including the pros and cons of each program, mortgage-insurance duration, property requirements, and an illustrative purchase example.
Real Colorado FHA Home Buying Stories
These anonymized transactions show how FHA financing can fit into a larger home-buying plan. Each story includes the buyer’s objective, challenge, financing strategy, and result.
Denver FHA purchase
From the mid-500s to first-time homeownership
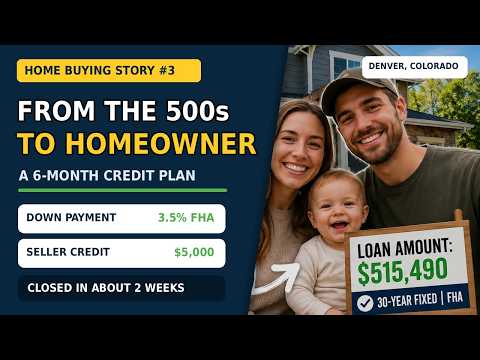
A six-month credit plan helped improve the lower qualifying score into the mid-600s. The family then purchased a $525,000 Denver home with FHA financing, 3.5% down, an approximately $5,000 seller credit, and a two-week contract-to-close timeline.
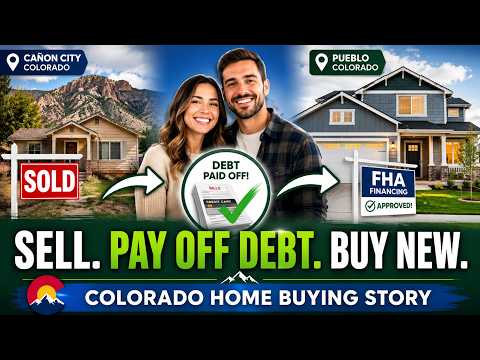
These buyers sold in Cañon City, allocated part of the proceeds to higher-interest debt, preserved enough for the new purchase, and used an FHA 30-year fixed mortgage plus a $7,000 seller credit to buy a Pueblo new-build home.
These are educational examples, not promises of approval, credit improvement, identical terms, or identical results.
How I Analyze an FHA Scenario
Confirm principal-residence occupancy and property eligibility.
Review credit history, income stability, assets, debts, and automated underwriting findings.
Check the correct county and unit loan limit.
Compare FHA with conventional, VA, and assistance options.
Calculate the base loan, financed mortgage insurance, monthly insurance, taxes, homeowners insurance, and association dues.
Compare seller credits, lender credits, gifts, and assistance.
Review appraisal and property-condition risk.
Calculate cash remaining after closing.
Review the expected ownership and refinance timeline.
Stress-test the payment and household budget.
Frequently Asked Questions About FHA Loans in Colorado
Are FHA loans only for first-time buyers?
No. FHA does not generally require first-time-buyer status, although an assistance program paired with FHA may have separate requirements.
Can I buy a condominium with FHA?
Potentially. The condominium project or individual unit must satisfy current FHA eligibility and lender requirements.
Can I use gift funds?
Potentially. The donor, relationship, source, transfer, and documentation must meet FHA and lender requirements.
Does FHA require a home inspection?
FHA requires an appraisal, not a buyer’s independent home inspection. A professional inspection is strongly worth considering.
Can the seller pay closing costs?
Potentially. FHA permits interested-party contributions within program limits for eligible costs. The contract, appraised value, and final charges must support the credit.
Can FHA mortgage insurance be removed?
The duration depends on the down payment, loan term, origination date, and current FHA rules. In some cases, refinancing into an eligible conventional mortgage may provide a path to eliminating FHA mortgage insurance, but the refinance must make economic sense.
Compare FHA Loans in Colorado With Conventional Financing
Compare the payment, mortgage insurance, cash to close, seller credits, assistance, and expected break-even period for your situation.
This page is for general educational purposes and is not a rate quote, approval, commitment to lend, credit-repair advice, financial advice, tax advice, or legal advice. FHA rules, loan limits, mortgage-insurance premiums, rates, costs, property requirements, seller-credit limits, documentation, and eligibility can change. All financing is subject to borrower, credit, income, asset, property, lender, FHA, and investor approval. Not all applicants or properties will qualify.
Good news for Colorado homebuyers: conventional loans up to $845,000 are becoming available through participating lenders before the official 2027 loan-limit announcement.
That is $12,250 above the current $832,750 national baseline for a one-unit home. For a buyer near that threshold, the additional room can create another f...
Michael and Melissa are always a pleasure to work with. They are extremely responsive, professional and work hard to get the best loan for us. I would recommend Colorado Mortgage to anyone. Thank you for another great experience!