 READ MORE
Fannie Mae loans in Colorado are conventional mortgages originated by lenders and evaluated under applicable Fannie Mae eligibility requirements. Fannie Mae does not lend money directly to homebuyers. It purchases eligible mortgages from approved lenders and helps provide liquidity, stability, and standardization in the U.S. housing-finance system.
The actual mortgage is originated by a lender, bank, credit union, or mortgage company, and the lender may apply its own requirements in addition to applicable Fannie Mae guidelines. The sections below explain the agency role, conforming limits, low-down-payment options, mortgage insurance, automated underwriting, and practical comparisons.
We can compare eligible Fannie Mae, Freddie Mac, FHA, VA, jumbo, and specialty structures using the actual property, credit, down payment, income, payment, and cash-to-close goals.
Fannie Mae is the common name for the Federal National Mortgage Association. It is a government-sponsored enterprise created by Congress to support the housing-finance system.
Fannie Mae purchases eligible residential mortgages from lenders and may pool loans into mortgage-backed securities that are sold to investors. This process helps lenders replenish capital so they can continue making new mortgages.
Fannie Mae explains its role at fanniemae.com. The Federal Housing Finance Agency regulates Fannie Mae and Freddie Mac and currently serves as their conservator.
Fannie Mae publishes detailed eligibility and underwriting requirements for mortgages it may purchase or securitize. Lenders use those requirements, automated underwriting tools, and their own policies to evaluate a loan.
The analysis may include credit history, income stability and documentation, employment and other qualifying income, monthly debts, debt-to-income ratio, down payment and reserves, gifts, property type and occupancy, appraisal, conforming loan limits, mortgage insurance, financed properties, title, ownership, and transaction structure.
A borrower does not need to memorize Fannie Mae guidelines. The loan professional should identify which requirements apply and compare them with other available programs.
A conforming loan is generally a mortgage that meets applicable Fannie Mae or Freddie Mac requirements and remains within the annual conforming loan limit for the county and number of units.
For 2026, the national baseline conforming loan limit for a one-unit property is $832,750 in most counties. Higher-cost areas can have higher limits, up to the national high-cost ceiling established by the Federal Housing Finance Agency.
The limit applies to the original loan amount, not directly to the purchase price. A home priced above the county limit may still use conforming financing when the down payment keeps the loan amount within the applicable limit.
Review the 2026 Colorado conforming-loan guide or the official FHFA conforming-loan-limit resource.
Subject to current requirements, eligible conventional financing may be available for primary-residence purchases, second homes, investment properties, rate-and-term refinances, cash-out refinances, one-to-four-unit residential properties, approved condominiums and planned-unit developments, eligible manufactured homes, and certain renovation transactions.
Property, occupancy, down-payment, reserve, appraisal, and pricing requirements vary.
Some eligible Fannie Mae conventional transactions can allow a down payment below 5 percent. Potential paths may include standard 97 percent loan-to-value options and income-restricted programs such as HomeReady, subject to current rules.
Low down payment does not automatically mean low cash to close. The buyer may also need funds for closing costs, prepaid taxes and insurance, escrow funding, inspections, moving, repairs, and reserves.
Review the dedicated Fannie Mae HomeReady guide and AMI lookup, then compare it with Freddie Mac Home Possible, FHA versus conventional financing, and Colorado down-payment-assistance programs.
Review Fannie Mae HomeReady, Freddie Mac Home Possible, the Colorado low-down-payment mortgage guide, and FHA versus conventional financing.
Conventional loans with a higher loan-to-value ratio may require private mortgage insurance. The cost and availability can depend on credit profile, loan-to-value ratio, occupancy, property type, loan term, and coverage requirements.
Private mortgage insurance is different from FHA mortgage insurance. Cancellation or termination may be available under applicable law, investor requirements, servicer rules, and property-value conditions. Read the Colorado mortgage-insurance guide before comparing a small-down-payment conventional loan with FHA.
Lenders commonly use an automated underwriting system to evaluate information from the mortgage application and credit report. The findings may identify eligibility, documentation, appraisal, reserve, and other conditions.
An automated approval is not the final loan approval. Information entered into the system must be accurate and supported by acceptable documents, and the property must satisfy all applicable requirements. Learn what happens during mortgage underwriting in Colorado.
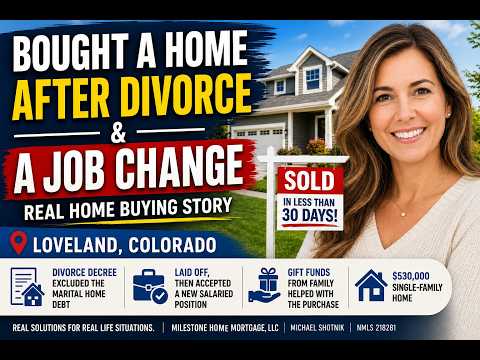
This anonymized Loveland transaction illustrates several conventional guideline concepts covered on this page: a mortgage assigned to a former spouse by court order, a new salaried job supported by an employment offer, family gift funds, and private mortgage insurance.
This story illustrates conventional guideline concepts. It is not a promise that every lender, automated-underwriting result, or conventional investor will treat another scenario identically.
| Area | Fannie Mae | Freddie Mac |
|---|---|---|
| Role | Purchases and securitizes eligible mortgages in the secondary market | Purchases and securitizes eligible mortgages in the secondary market |
| Direct consumer lending | Does not originate mortgages directly to borrowers | Does not originate mortgages directly to borrowers |
| Guidelines | Uses Fannie Mae eligibility, underwriting, and delivery requirements | Uses Freddie Mac eligibility, underwriting, and delivery requirements |
| Automated underwriting | Desktop Underwriter is commonly used | Loan Product Advisor is commonly used |
| Borrower result | May fit a particular income, asset, property, or transaction detail | May fit a different income, asset, property, or transaction detail |
The two systems overlap substantially, but they are not identical. A mortgage broker can compare eligible lender and agency paths when one produces a more workable result.
| Feature | Fannie Mae conventional | FHA |
|---|---|---|
| Insurance structure | Private mortgage insurance may apply based on loan-to-value and program | Upfront and annual FHA mortgage insurance generally apply |
| Credit sensitivity | Pricing and mortgage insurance can be highly credit-sensitive | May provide additional flexibility in some credit scenarios |
| Occupancy | May support primary, second-home, and investment transactions | Generally requires principal-residence occupancy |
| Property standards | Conventional appraisal and property eligibility apply | FHA appraisal and minimum property requirements apply |
| Best fit | Depends on credit, down payment, property, mortgage insurance, and pricing | Depends on the same factors plus FHA insurance and property requirements |
Review the full FHA loan guide and compare actual numbers rather than assuming one program is always cheaper.
No. Consumers apply through an approved lender, mortgage bank, bank, credit union, or mortgage broker relationship. Fannie Mae operates in the secondary mortgage market.
Fannie Mae does not publish one retail rate that every borrower receives. Mortgage pricing reflects bond-market conditions, lender execution, loan characteristics, credit, property, occupancy, lock period, points, and other factors.
No. A conventional loan is not government-insured, but it may follow Fannie Mae, Freddie Mac, jumbo, portfolio, or other investor requirements.
The company collecting payments may be the original lender or a separate servicer. Servicing can transfer even when the underlying mortgage remains subject to the same note and security instrument.
Potentially. The lender evaluates tax returns, business and personal income, ownership, liquidity, debts, trends, and current requirements. Compare standard qualification with other self-employed mortgage options.
The agency name matters less than the final payment, costs, mortgage insurance, cash to close, documentation, appraisal, and approval reliability for the borrower and property.
Schedule a Colorado Mortgage Review
Explore Mortgage Programs
Michael Shotnik
Broker | Owner, Milestone Home Mortgage
NMLS 218281
303-800-4595
This page is for general educational purposes and is not a rate quote, approval, commitment to lend, legal advice, divorce advice, employment advice, or financial advice. Fannie Mae, lender, appraisal, mortgage-insurance, loan-limit, credit, income, asset, debt, and property requirements can change. All financing is subject to borrower, credit, income, asset, property, lender, agency, and investor approval. Not all applicants or properties will qualify.
READ MORE
Michael and Melissa are always a pleasure to work with. They are extremely responsive, professional and work hard to get the best loan for us. I would recommend Colorado Mortgage to anyone. Thank you for another great experience!
Milestone Home Mortgage LLC NMLS #2588937. Michael Shotnik NMLS: 218281, CO License: 100017466. Not licensed in Alaska or New York. To check license status of mortgage loan originator, visit D.O.R.A. and NMLS consumer access.