Fannie Mae Loans in Colorado: How Conventional Financing Works
Fannie Mae loans in Colorado are conventional mortgages originated by lenders and evaluated under applicable Fannie Mae eligibility requirements. Fannie Mae does not lend money directly to homebuyers. It purchases eligible mortgages from approved lenders and helps provide liquidity, stability, and standardization in the U.S. housing-finance system.
The actual mortgage is originated by a lender, bank, credit union, or mortgage company, and the lender may apply its own requirements in addition to applicable Fannie Mae guidelines. The sections below explain the agency role, conforming limits, low-down-payment options, mortgage insurance, automated underwriting, and practical comparisons.
Compare Fannie Mae conventional financing with other eligible mortgage paths using the complete transaction.
Fannie Mae Loans in Colorado: On This Page
Compare Conventional Mortgage Options
We can compare eligible Fannie Mae, Freddie Mac, FHA, VA, jumbo, and specialty structures using the actual property, credit, down payment, income, payment, and cash-to-close goals.
Fannie Mae is the common name for the Federal National Mortgage Association. It is a government-sponsored enterprise created by Congress to support the housing-finance system.
Fannie Mae purchases eligible residential mortgages from lenders and may pool loans into mortgage-backed securities that are sold to investors. This process helps lenders replenish capital so they can continue making new mortgages.
Fannie Mae explains its role at fanniemae.com. The Federal Housing Finance Agency regulates Fannie Mae and Freddie Mac and currently serves as their conservator.
How Do Fannie Mae Loans in Colorado Affect a Mortgage?
Fannie Mae publishes detailed eligibility and underwriting requirements for mortgages it may purchase or securitize. Lenders use those requirements, automated underwriting tools, and their own policies to evaluate a loan.
The analysis may include credit history, income stability and documentation, employment and other qualifying income, monthly debts, debt-to-income ratio, down payment and reserves, gifts, property type and occupancy, appraisal, conforming loan limits, mortgage insurance, financed properties, title, ownership, and transaction structure.
A borrower does not need to memorize Fannie Mae guidelines. The loan professional should identify which requirements apply and compare them with other available programs.
What Is a Conforming Loan?
A conforming loan is generally a mortgage that meets applicable Fannie Mae or Freddie Mac requirements and remains within the annual conforming loan limit for the county and number of units.
For 2026, the national baseline conforming loan limit for a one-unit property is $832,750 in most counties. Higher-cost areas can have higher limits, up to the national high-cost ceiling established by the Federal Housing Finance Agency.
The limit applies to the original loan amount, not directly to the purchase price. A home priced above the county limit may still use conforming financing when the down payment keeps the loan amount within the applicable limit.
Subject to current requirements, eligible conventional financing may be available for primary-residence purchases, second homes, investment properties, rate-and-term refinances, cash-out refinances, one-to-four-unit residential properties, approved condominiums and planned-unit developments, eligible manufactured homes, and certain renovation transactions.
Property, occupancy, down-payment, reserve, appraisal, and pricing requirements vary.
Low-Down-Payment Fannie Mae Options
Some eligible Fannie Mae conventional transactions can allow a down payment below 5 percent. Potential paths may include standard 97 percent loan-to-value options and income-restricted programs such as HomeReady, subject to current rules.
Low down payment does not automatically mean low cash to close. The buyer may also need funds for closing costs, prepaid taxes and insurance, escrow funding, inspections, moving, repairs, and reserves.
Conventional loans with a higher loan-to-value ratio may require private mortgage insurance. The cost and availability can depend on credit profile, loan-to-value ratio, occupancy, property type, loan term, and coverage requirements.
Private mortgage insurance is different from FHA mortgage insurance. Cancellation or termination may be available under applicable law, investor requirements, servicer rules, and property-value conditions. Read the Colorado mortgage-insurance guide before comparing a small-down-payment conventional loan with FHA.
Fannie Mae Automated Underwriting
Lenders commonly use an automated underwriting system to evaluate information from the mortgage application and credit report. The findings may identify eligibility, documentation, appraisal, reserve, and other conditions.
An automated approval is not the final loan approval. Information entered into the system must be accurate and supported by acceptable documents, and the property must satisfy all applicable requirements. Learn what happens during mortgage underwriting in Colorado.
See Conventional Underwriting in a Real Colorado Purchase
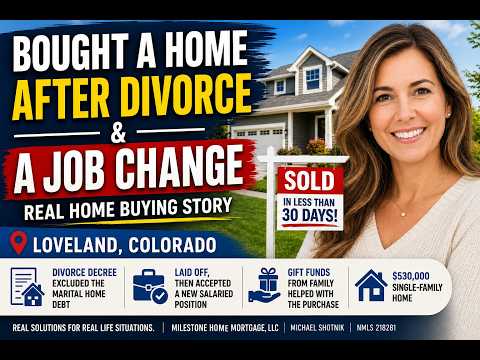
This anonymized Loveland transaction illustrates several conventional guideline concepts covered on this page: a mortgage assigned to a former spouse by court order, a new salaried job supported by an employment offer, family gift funds, and private mortgage insurance.
Loveland conventional purchase
Buying after divorce, a layoff, and a new job
The buyer remained named on the former marital mortgage, then experienced a layoff and accepted a new salaried position. Divorce documentation, projected fixed income from an eligible employment offer, buyer funds, and a family gift were coordinated for a $530,000 purchase with an approximately $430,000 conventional 30-year fixed mortgage.
This story illustrates conventional guideline concepts. It is not a promise that every lender, automated-underwriting result, or conventional investor will treat another scenario identically.
Fannie Mae Versus Freddie Mac
Area
Fannie Mae
Freddie Mac
Role
Purchases and securitizes eligible mortgages in the secondary market
Purchases and securitizes eligible mortgages in the secondary market
Direct consumer lending
Does not originate mortgages directly to borrowers
Does not originate mortgages directly to borrowers
Guidelines
Uses Fannie Mae eligibility, underwriting, and delivery requirements
Uses Freddie Mac eligibility, underwriting, and delivery requirements
Automated underwriting
Desktop Underwriter is commonly used
Loan Product Advisor is commonly used
Borrower result
May fit a particular income, asset, property, or transaction detail
May fit a different income, asset, property, or transaction detail
The two systems overlap substantially, but they are not identical. A mortgage broker can compare eligible lender and agency paths when one produces a more workable result.
Fannie Mae Versus FHA
Feature
Fannie Mae conventional
FHA
Insurance structure
Private mortgage insurance may apply based on loan-to-value and program
Upfront and annual FHA mortgage insurance generally apply
Credit sensitivity
Pricing and mortgage insurance can be highly credit-sensitive
May provide additional flexibility in some credit scenarios
Occupancy
May support primary, second-home, and investment transactions
Generally requires principal-residence occupancy
Property standards
Conventional appraisal and property eligibility apply
FHA appraisal and minimum property requirements apply
Best fit
Depends on credit, down payment, property, mortgage insurance, and pricing
Depends on the same factors plus FHA insurance and property requirements
Review the full FHA loan guide and compare actual numbers rather than assuming one program is always cheaper.
Frequently Asked Questions About Fannie Mae Loans in Colorado
Can I apply directly to Fannie Mae for a mortgage?
No. Consumers apply through an approved lender, mortgage bank, bank, credit union, or mortgage broker relationship. Fannie Mae operates in the secondary mortgage market.
Does Fannie Mae set mortgage rates?
Fannie Mae does not publish one retail rate that every borrower receives. Mortgage pricing reflects bond-market conditions, lender execution, loan characteristics, credit, property, occupancy, lock period, points, and other factors.
Is every conventional loan a Fannie Mae loan?
No. A conventional loan is not government-insured, but it may follow Fannie Mae, Freddie Mac, jumbo, portfolio, or other investor requirements.
Who services the loan after closing?
The company collecting payments may be the original lender or a separate servicer. Servicing can transfer even when the underlying mortgage remains subject to the same note and security instrument.
Can a self-employed borrower use a Fannie Mae loan?
Potentially. The lender evaluates tax returns, business and personal income, ownership, liquidity, debts, trends, and current requirements. Compare standard qualification with other self-employed mortgage options.
Compare the Actual Mortgage Options
The agency name matters less than the final payment, costs, mortgage insurance, cash to close, documentation, appraisal, and approval reliability for the borrower and property.
Michael Shotnik Broker | Owner, Milestone Home Mortgage NMLS 218281 303-800-4595
This page is for general educational purposes and is not a rate quote, approval, commitment to lend, legal advice, divorce advice, employment advice, or financial advice. Fannie Mae, lender, appraisal, mortgage-insurance, loan-limit, credit, income, asset, debt, and property requirements can change. All financing is subject to borrower, credit, income, asset, property, lender, agency, and investor approval. Not all applicants or properties will qualify.
A lower house payment starts with the decisions you make before you buy.
When mortgage rates stretch your budget, shopping for a home needs to include more than the asking price. We need to look at how you buy, which property you choose and every meaningful expense that will go into your monthly payment.
Michael and Melissa are always a pleasure to work with. They are extremely responsive, professional and work hard to get the best loan for us. I would recommend Colorado Mortgage to anyone. Thank you for another great experience!